The short answer
To buy a home in Querétaro with Infonavit you need current formal employment with contributions to the institute and must meet the pre-qualification shown in your account. With the approved amount you choose a home, an appraisal is done, you sign the deed before a notary and the institute pays the seller. Cofinavit can add a bank loan.
Infonavit is the institute that manages private-sector workers' housing savings and lends against them. It was founded in 1972. This guide explains in general terms how it is used to buy in Querétaro; exact requirements and amounts should always be checked through the institute's official channels.
Who can use Infonavit?
Workers in formal jobs whose employer pays contributions to the institute. Those contributions build up in your housing sub-account. Pre-qualification weighs factors such as salary, age and contribution history; the result appears in your online account.
Source: Wikipedia: Infonavit
Which loan types exist?
Besides the traditional loan, the institute offers schemes where a financial institution adds funds, such as Cofinavit, and options for proving additional income. Names and terms change over time, so check the current offer before choosing.
Source: Wikipedia: Infonavit
What are the steps to buy?
The general process is similar across Mexico, with local details the notary will explain.
- Check your pre-qualification and estimated amount.
- Complete any course or workshop the institute requires.
- Choose the home and confirm it meets the loan conditions.
- Order the appraisal from an authorized appraisal firm.
- Assemble the file and sign the deed before a notary.
- The institute pays the seller and payroll deductions begin.
Which homes can you buy in Querétaro?
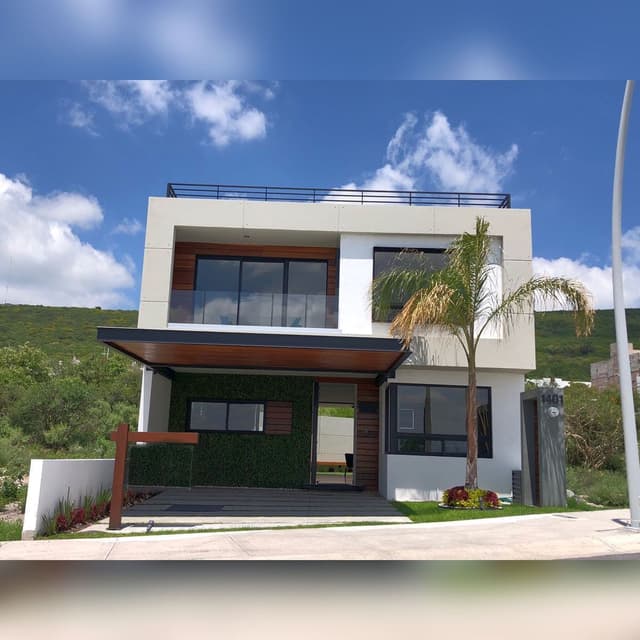
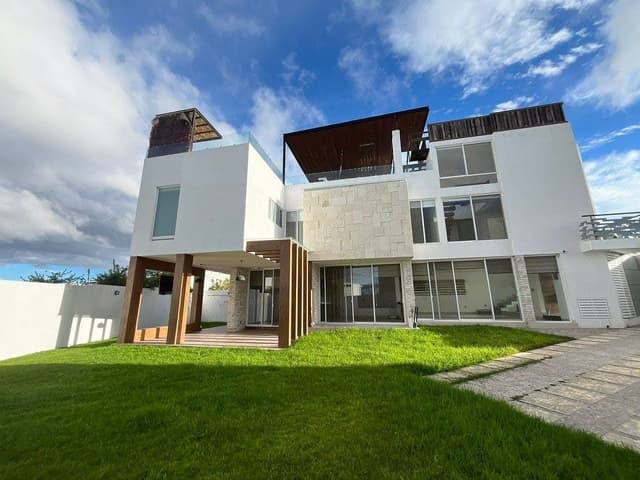
New or resale homes that meet the loan's technical and legal conditions. In Querétaro there are options in areas such as El Refugio, La Vista or Milenio III; any gap between the price and your loan is covered with savings or a co-financing scheme.
More detail
If you buy pre-construction, confirm you can draw the loan at handover and that the home will have what the appraisal needs, such as connected utilities and an individual deed.
How do you avoid scams?
Infonavit procedures go through its official channels. Be wary of anyone who charges to process your loan or asks for deposits into personal accounts. Profeco, the consumer protection agency, offers guidance on home purchases.
Source: Profeco (gob.mx)
How do you compare it with other options?
Compare the total cost of the loan with a bank mortgage or a combined scheme. Banco de México provides a calculator for the total annual cost (CAT) of loans that puts them on the same scale.
Source: Banco de México: Calculadora del Costo Anual Total (CAT)
Which common mistakes should you avoid?
Choosing a house before knowing your real loan amount, forgetting closing costs, putting down a reservation without checking the home qualifies, or signing without reading the insurance and deduction terms. All of these are avoided with early information.
We suggest pre-qualifying first, reviewing options within that range and asking the notary for an estimate before committing any money.